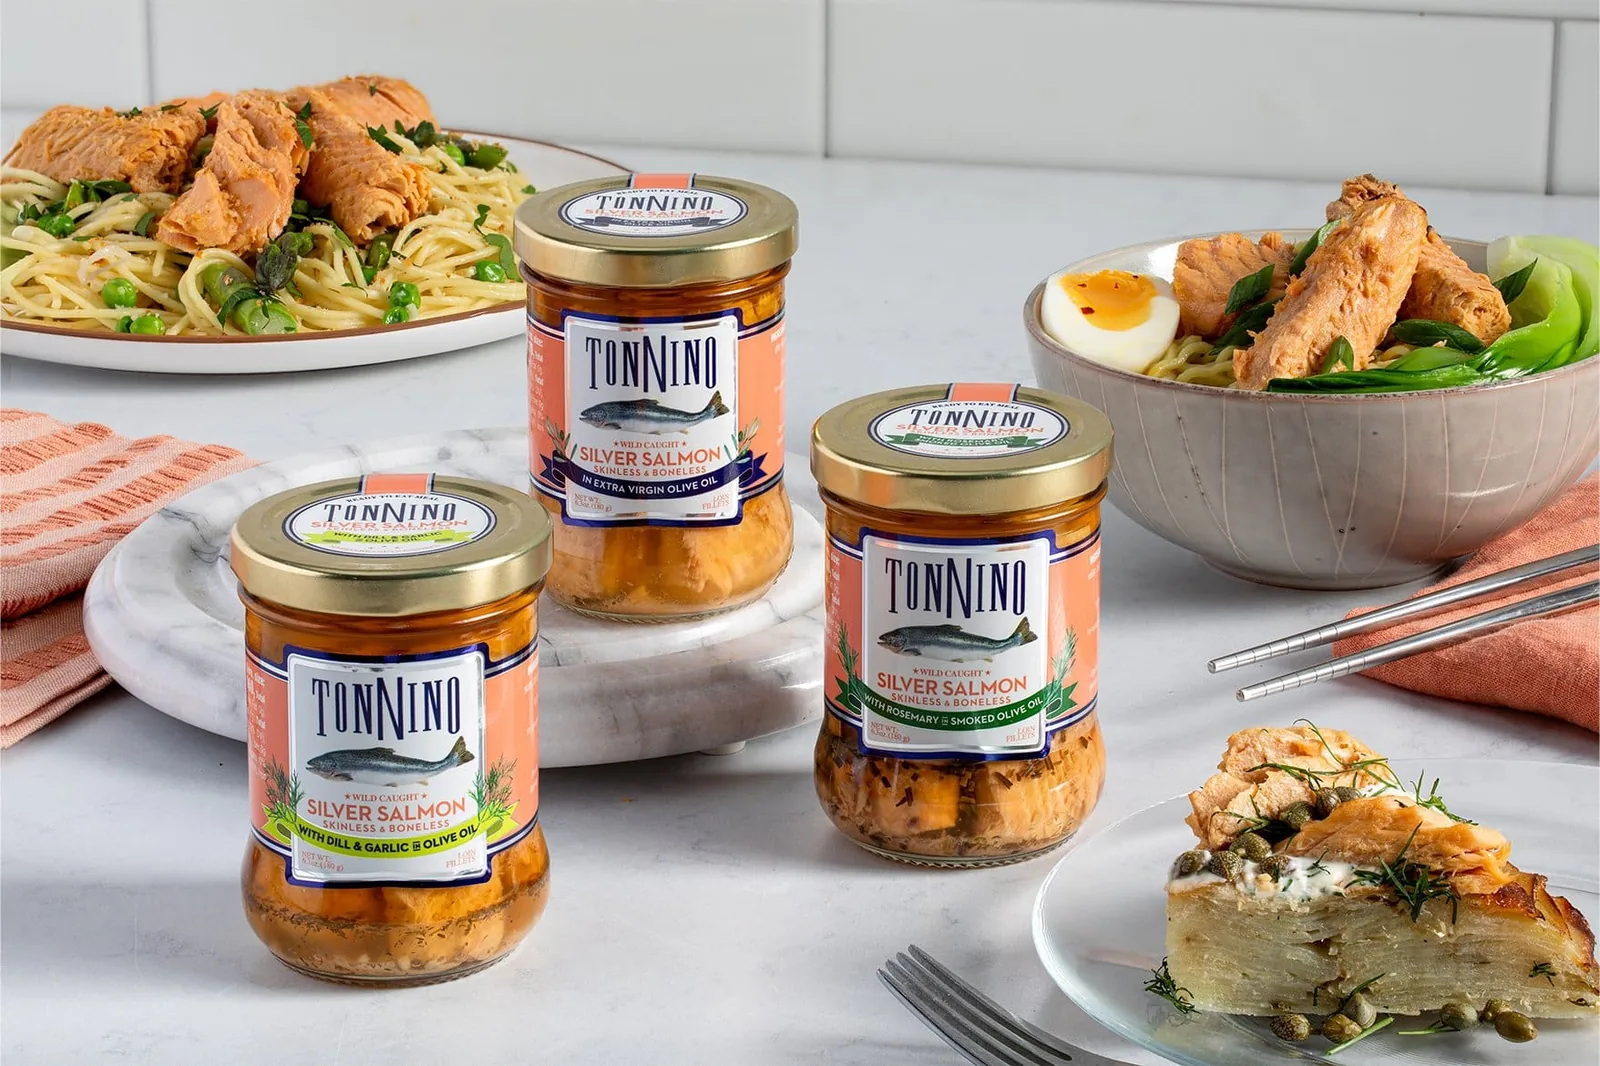
Seafood sells on trust more than anything else in the store. People want to know what it is, where it came from, and what to do with it by dinner. We build the brand, packaging and media that answer all three.
The category looks healthy. It isn't. Fresh volume fell 0.6% last year, frozen fell 1.9%, and both still posted dollar gains. That's price doing the work, not appetite.
What growth there is comes from a few people. Ten percent of shoppers buy forty percent of the fish, in baskets two and a half times the store average.
Everyone else is standing in the aisle not buying, and it isn't about taste. 55% don't believe the label. 62% of Gen Z want dinner in twenty minutes. It's doubt.
So there are two jobs. Be the default for the few. Take one doubt off the table for the many. Most brands only run the first.
FMI's Power of Seafood 2026 found ten percent of shoppers drive forty percent of retail seafood purchases. So the first question is whether you are built for them or for everyone. We start with the shelf, the price gap and who is actually putting you in the basket.
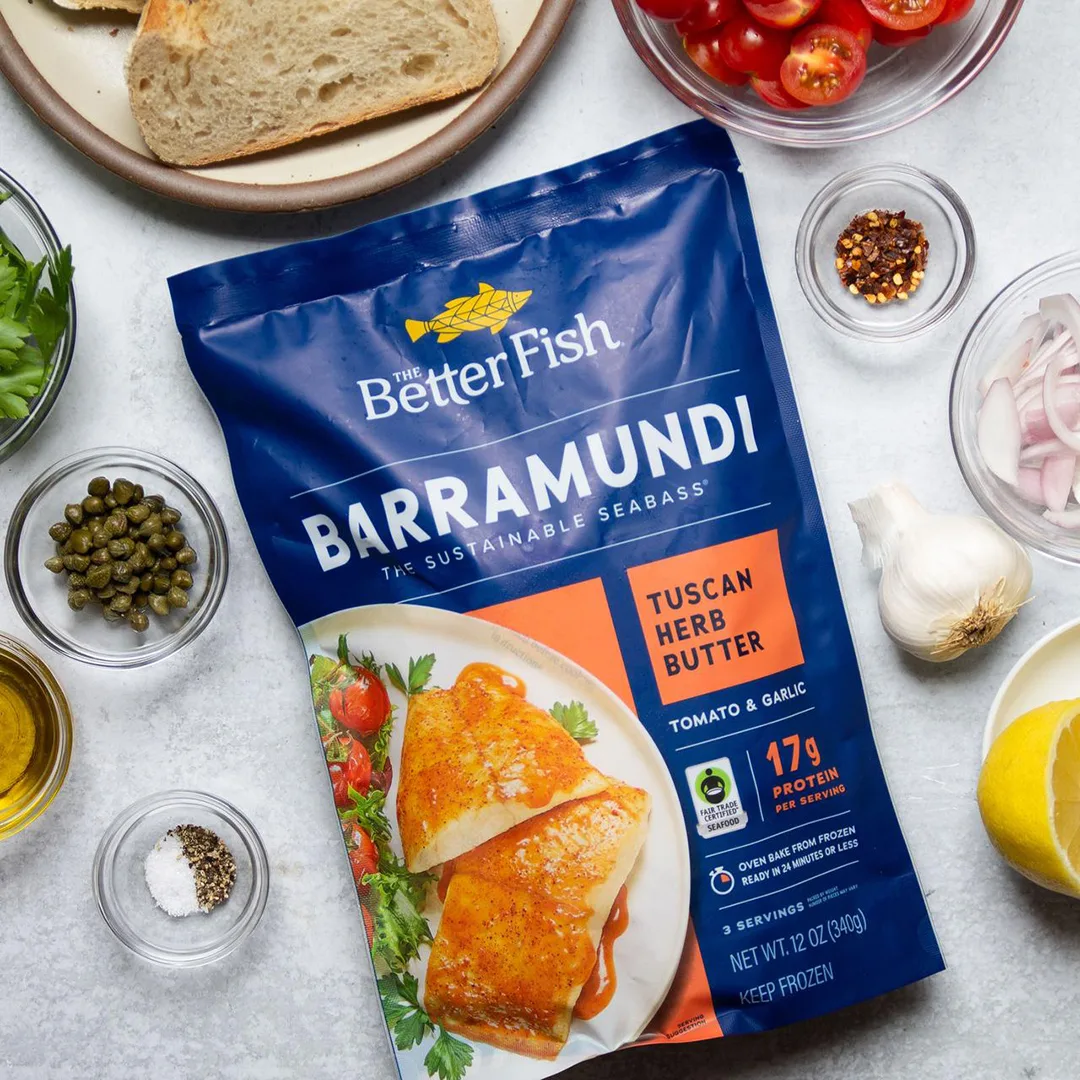
The pack is the only media you are guaranteed. We work the hierarchy, the claims and the certification marks so it reads in two seconds from four feet away.
Volume fell across both fresh and frozen last year while value climbed on price alone, which means growth has to come from trial and repeat rather than a bigger ticket. Retail media and paid run against the species and the seasons that actually move.
A seafood brand lives on the shopper who comes back, not the one who tries it once. We track sell-through where the data exists, and work the retention levers where it does not.
Most campaigns show measurable lift in the first thirty days, though the real compounding effect of listing optimization and retail media together tends to show up over a full quarter.
Yes. A lot of our seafood clients never touch end consumers directly. We still build the retail media and content programs that move product off shelf, even when the brand itself has no storefront.
Trust is the whole game. Shoppers are doubting the label more than any other grocery category, so almost everything we build is aimed at closing that specific gap rather than generic awareness.
We work with what you already hold, MSC, ASC, BAP or a fishery improvement project, and make it legible on pack and in your media. We are not a certifier and we will not write a claim you cannot substantiate.
Both, and they are different jobs. Frozen is $8.6 billion against fresh at $8.3 billion, but FMI's 2026 figures show volume fell in both while value rose on price alone. Frozen competes on convenience and stock-up, fresh competes on the perception of quality.
Yes. Foodservice buys on spec and consistency, retail buys on the shopper, and the two need different stories even when it is the same fish. We will tell you which one your pack and your site are currently written for.
Tell us what you're building and we'll get back to you.